ASML vs. SK Hynix: What Revenue Trends Reveal to Investors About These Artificial Intelligence Companies
 2026-10-01 19:17
•Robert Izquierdo •The Motley Fool
•••••••• ••
Axe Cap view
AI Chipmakers: Patience with ASML, Opportunity in SK Hynix
ASML's slow but steady growth contrasts with SK Hynix’s rapid revenue surge, highlighting different ways to play AI demand.
ASML and SK Hynix are both key players in the race for AI dominance, but their revenue story doesn’t look the same. ASML, with its near-monopoly on extreme ultraviolet (EUV) lithography machines, grows predictably and steadily because building its equipment takes time—think of it as the specialist tools supplier for AI chips. Meanwhile, SK Hynix is the high-speed memory chip producer benefiting from skyrocketing AI data needs and memory prices, showing a much faster revenue ramp. For South African investors, direct exposure to these companies is limited, but the USD/ZAR exchange rate provides a window. A stronger rand against the dollar can soften imported tech costs and benefit local banks like Standard Bank and FirstRand through improved consumer affordability. My concern: SK Hynix’s rapid growth depends heavily on AI memory demand holding up, which can reverse if AI progress stalls or memory prices drop. this is just our opinion and not financial advice
Wait on ASML—it’s a steady but slow grower without a South African listed proxy. Watch SK Hynix for an entry point if the USD/ZAR weakens, as the rand’s strength could dampen local tech demand and pressure related sectors. For local exposure, consider selective buys in financial stocks like Standard Bank that may benefit indirectly.
- USD/ZAR
- Standard Bank
- FirstRand
- AI demand slowdown affecting memory prices
- USD/ZAR volatility impacting local tech and banking sectors
6/10
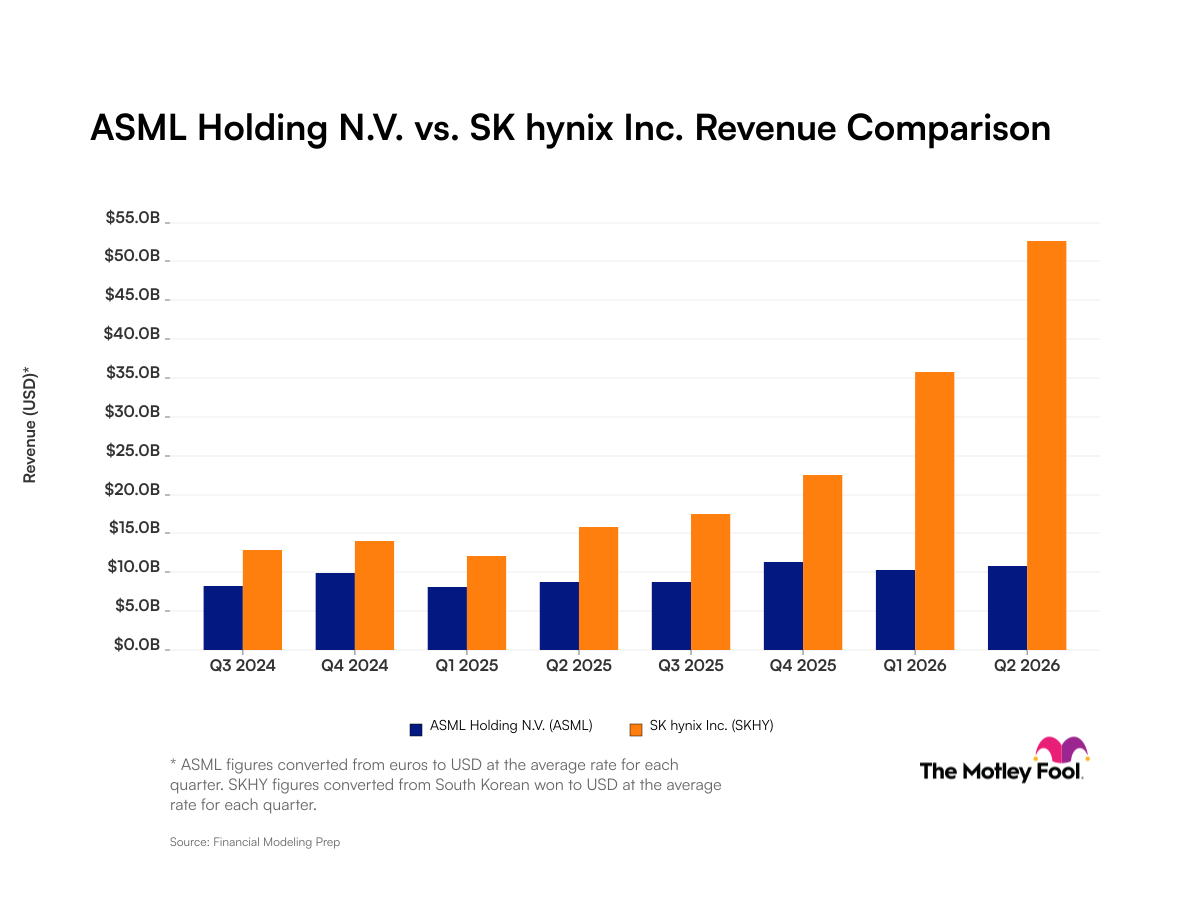
SK Hynix and ASML are both benefiting from AI demand, but their revenue trajectories differ significantly. ASML shows steady, gradual quarterly growth due to long manufacturing timelines for EUV lithography equipment, while SK Hynix demonstrates rapid acceleration in memory chip sales driven by surging demand and rising memory prices. SK Hynix's Q2 2026 revenue reached $52.6 billion compared to ASML's $10.8 billion, highlighting divergent growth patterns in the semiconductor supply chain.
Our take is based on reporting first published by The Motley Fool.